Banking in Saudi Arabia Reimagined: Instant Debit Cards, Digital Accounts, and the SWIFT Infrastructure
Saudi Arabia's banking sector has undergone a significant digital transformation, making financial services faster, more accessible, and increasingly efficient for individuals and businesses alike. This article explores the evolution of digital banking, including online account opening, Mada card issuance, and international transfers through the SWIFT network. It also examines how technological innovation operates alongside strict regulatory compliance to safeguard financial stability. Finally, the article highlights how EL-LWAA Law Firm supports investors by helping them navigate banking regulations and maintain legally compliant financial operations.
Digital Banking Services in Saudi Arabia: Balancing Accessibility and Regulatory Compliance
Saudi Arabia's banking sector has undergone a remarkable transformation in recent years. Traditional banking procedures that once relied on lengthy paperwork and branch visits have largely been replaced by an integrated digital ecosystem that combines speed, convenience, and strict regulatory oversight.
This transformation has not only improved access to financial services but has also reshaped how individuals, entrepreneurs, and investors interact with financial institutions. Today, customers can complete most banking transactions digitally while remaining within a comprehensive regulatory framework designed to promote transparency, financial stability, and consumer protection.
How Digital Banking Has Simplified Financial Services
The Saudi banking sector has invested heavily in digital innovation, making many banking services faster and more accessible than ever before.
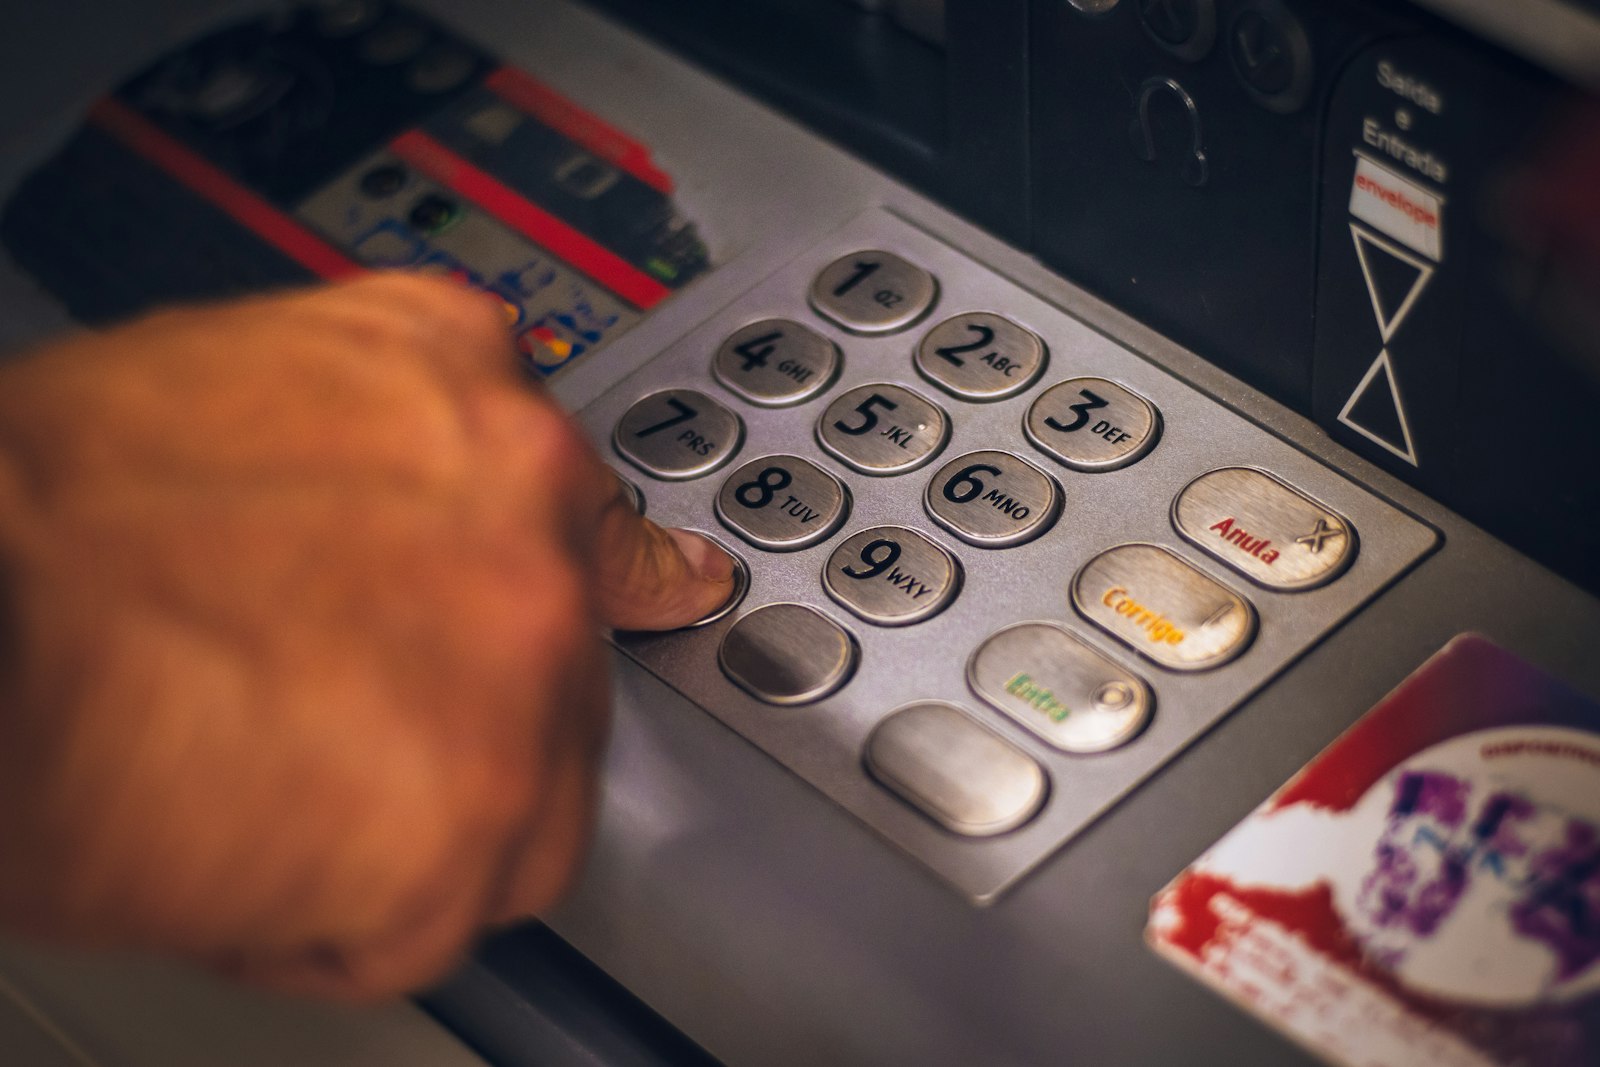
One of the clearest examples is the issuance of Mada debit cards, which can now be obtained within minutes through self-service kiosks available at bank branches and shopping centers. These kiosks also enable customers to update personal information, replace cards, activate services, and reset PIN codes without requiring assistance from branch staff.
This streamlined approach reflects the banking sector's commitment to delivering a more efficient customer experience while reducing unnecessary administrative procedures.
Opening a Bank Account Online
Many Saudi banks now allow customers to open bank accounts entirely through their mobile applications or online banking platforms, provided that several basic requirements are met, including:
A valid National ID or residency permit (Iqama).
A verified mobile phone number.
Active integration with relevant government digital platforms.
Successful electronic identity verification.
Once the initial account has been established, customers gain access to a comprehensive suite of digital banking services, including account management, card issuance, domestic and international transfers, and other financial services—all without the need to visit a physical branch except in limited circumstances.
Banks Have Become Digital Financial Platforms
Modern banks in Saudi Arabia are no longer defined by their physical branches. Instead, they have evolved into comprehensive digital platforms that allow customers to access banking services anytime and from virtually anywhere.
This evolution has significantly enhanced operational efficiency and customer convenience while maintaining strict compliance with regulatory requirements. Digital transformation has therefore improved service delivery without compromising the integrity or security of the financial system.
Understanding International Transfers Through the SWIFT System
International money transfers rely on the SWIFT network, one of the world's most widely used financial messaging systems.
Rather than transferring funds directly between banks, SWIFT securely exchanges standardized financial messages containing essential transaction information, including:
Sender and beneficiary details.
Transfer amount.
Currency.
Receiving bank information.
The bank's unique SWIFT code.
The SWIFT code plays a critical role in ensuring that international transfers reach the correct financial institution accurately and securely, making it an essential component of cross-border banking transactions.
International Transfer Timeframes and Settlement Currency
Most international transfers originating from Saudi Arabia are processed using the U.S. dollar as an intermediary settlement currency, a practice that contributes to efficient processing, particularly given the long-standing peg between the Saudi Riyal and the U.S. dollar.
Under normal circumstances, international transfers are completed within one to three business days. However, the exact processing time may vary depending on several factors, including:
The sending bank.
The receiving bank.
The destination country.
Time zone differences and public holidays.
Required compliance and verification procedures.
Transfer fees may also vary depending on the financial institution, destination, and type of transfer requested.
Balancing Convenience with Regulatory Compliance
Saudi Arabia's banking model demonstrates that digital convenience and regulatory oversight are complementary rather than conflicting objectives.
Although customers can now access financial services with unprecedented ease, every banking transaction remains subject to comprehensive regulatory controls designed to:
Promote financial transparency.
Combat money laundering and financial crimes.
Protect customers.
Strengthen financial stability.
Ensure compliance with applicable banking regulations.
Accordingly, technological advancement has enhanced—not replaced—the compliance mechanisms that safeguard the integrity of the financial system.
How EL-LWAA Law Firm Supports Investors in Banking Matters
Successfully operating within Saudi Arabia's financial environment requires more than simply opening a bank account. Investors and business owners must also understand the legal and regulatory framework governing their banking relationships.
Within this context, EL-LWAA Law Firm serves as a trusted legal partner by helping investors understand the legal structure surrounding banking operations, organize their financial activities in compliance with applicable regulations, and minimize the risk of delays or operational challenges arising from compliance requirements.
The firm's experience in connecting operational business needs with legal obligations enables clients to establish stable banking relationships, improve financial management practices, and navigate regulatory requirements with greater confidence.
Conclusion
Saudi Arabia's banking sector has successfully achieved an advanced balance between digital innovation and regulatory discipline. Banking services have become faster, more efficient, and increasingly accessible, while maintaining the robust compliance standards necessary to preserve the integrity and stability of the financial system.
As digital banking continues to evolve, understanding the legal and regulatory framework governing financial transactions remains essential for both individuals and businesses seeking to make the most of these modern financial services.
In Saudi Arabia, speed may define the customer experience—but compliance remains the foundation of every secure and sustainable banking relationship.